

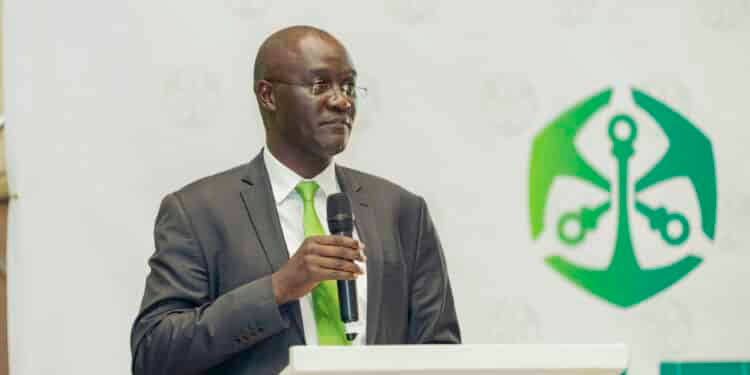
Old Mutual Holdings chief executive Arthur Oginga is taking a tougher position on one of Kenya’s most persistent insurance industry problems — price competition that can leave insurers carrying risks they are not adequately paid to cover.
In an interview following the insurer’s half-year results, Mr Oginga defended the company’s decision to walk away from some poorly priced business, arguing that cheaper insurance is not necessarily better for customers if the premiums do not reflect the underlying risk.
Old Mutual’s medical business returned to profitability in the first half of 2026 after recording losses in previous periods. The company attributed the improvement partly to repricing its medical portfolio and dropping accounts it considered unsustainable.
Question: How serious is price undercutting in insurance?
Mr Oginga says lower prices are not inherently bad.
The problem, he argues, arises when prices are reduced without corresponding improvements in efficiency or operating costs.
“If prices are lower because a company has found a better way of operating, customers benefit,” he says. But when premiums are simply pushed down to win business, the result can be damaging for both insurers and policyholders.
His concern is particularly evident in medical insurance, where claims can rise sharply and insurers have to meet treatment costs regardless of how aggressively premiums were priced.
Old Mutual has therefore taken a case-by-case approach to its portfolio.
Some customers left after the company revised premiums, but Mr Oginga says retaining loss-making accounts simply to protect market share would not make business sense.
Question: Does walking away from customers make commercial sense?
For Mr Oginga, the answer is yes if the alternative is continuing to lose money.
The strategy marks a shift from pursuing growth at almost any cost to placing greater emphasis on profitable growth.
The approach appears to have paid off. Old Mutual Holdings posted a net profit of Sh882 million in the six months to June 2026, compared with Sh5 million in the same period a year earlier.
But pricing is not the only challenge facing the insurer.
Fraud remains a concern, increasing the cost of claims and putting additional pressure on premiums.
The company is also reviewing its property portfolio, including plans to dispose of some real estate assets as it seeks to focus capital on areas where it can generate stronger returns.
For Mr Oginga, the broader lesson is that insurers must be disciplined about where they deploy capital.
The industry has traditionally been highly competitive, with companies fighting for corporate accounts and individual policyholders.
But aggressive competition can become counterproductive if insurers continuously sacrifice margins.
Question: What should the industry do differently?
Mr Oginga believes the answer lies in better pricing, stronger controls and greater efficiency.
Insurance companies must understand the risks they are taking and price them accordingly.
Technology can also play a role in improving underwriting, claims management and fraud detection.
For customers, the implication may be that the cheapest policy will not always be the best option.
An insurer that prices realistically is more likely to have the financial capacity to honour claims when customers need it.
For Mr Oginga, therefore, the future of insurance is not simply about gaining more customers.
It is about gaining the right customers, pricing their risks properly and building businesses capable of remaining profitable over the long term.