

Kenya’s banking sector ended 2025 with more accounts holding at least half a million shillings, offering a revealing — though incomplete — picture of how financial wealth is distributed across the country.
The number of commercial-bank deposit accounts with balances of Sh500,000 or more rose to 781,977 in December 2025, from 739,803 a year earlier. That is an increase of 42,174 accounts, or about 5.7 per cent, according to the Central Bank of Kenya’s 2025 Bank Supervision Annual Report.
But the figures need careful reading. They count bank accounts, not people, meaning the data cannot be used to say that 781,977 Kenyans have more than Sh500,000 in savings. Individuals, businesses and institutions can hold multiple accounts.
The numbers nevertheless provide an interesting snapshot of Kenya’s financial landscape and the concentration of larger deposits within the banking system.
Equity, KCB and Co-operative lead the high-balance accounts
Equity Bank recorded the highest number of commercial-bank accounts with balances of Sh500,000 or more, at 141,259.
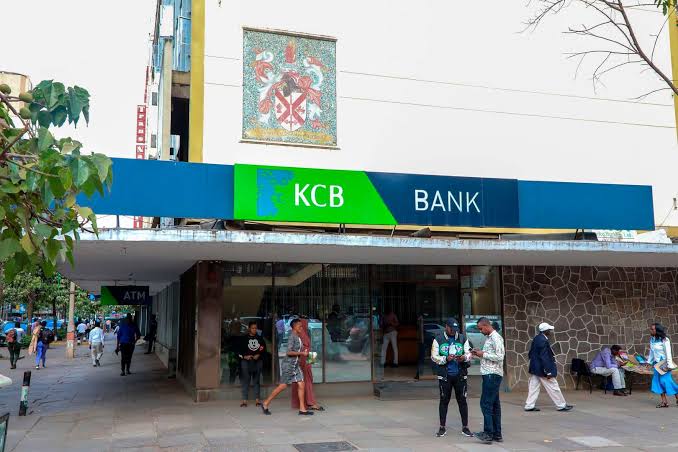
KCB Bank followed with 130,915, while Co-operative Bank recorded 94,016.
Absa Bank had 57,470 such accounts, followed by NCBA with 45,417, I&M Bank with 41,808 and Diamond Trust Bank with 40,434.
Family Bank recorded 26,930, Stanbic Bank 24,354 and National Bank of Kenya 17,538.
The top 10 banks together accounted for 620,141 of the 781,977 high-balance commercial-bank accounts recorded at the end of 2025.
The figures also demonstrate that the number of customers a bank serves does not necessarily correspond to the number of relatively high-value accounts it holds.
The Sh500,000 threshold does not measure personal wealth
The headline figure can easily create the impression that Kenya has fewer than 800,000 people with at least Sh500,000 in the bank.
The CBK data does not establish that.
The regulator’s table records accounts according to their balances. A person could have Sh300,000 in one account and Sh300,000 in another, for example, without either account individually crossing the Sh500,000 threshold.
The same applies to companies and institutions that may operate several accounts.
The data should therefore be viewed as a measure of deposit-account balances, rather than a census of wealthy Kenyans.
When microfinance banks are included, the number of accounts with balances of Sh500,000 or more rises to 788,853.
Most bank accounts remain below Sh500,000
The contrast becomes more striking when the lower-balance accounts are considered.
Commercial banks recorded 79.88 million accounts with balances below Sh500,000 in December 2025, compared with 781,977 accounts at or above the threshold. The commercial-bank total stood at 80.68 million accounts at the end of the year.
However, the sharp change in the total number of accounts between 2024 and 2025 requires caution.
Commercial banks recorded 114.24 million accounts in the corresponding 2024 table, compared with 80.68 million in 2025. The CBK notes that changes in account numbers were affected by developments in account reporting and consolidation, meaning the year-on-year movement should not simply be interpreted as millions of Kenyans suddenly losing or closing accounts.
This is particularly important when using account numbers as a proxy for financial inclusion or inequality.
Kenya’s banking deposits grew strongly
The high-balance account figures came during a year in which the broader banking sector recorded substantial growth in deposits.
Customer deposits in commercial banks increased by 11.6 per cent, rising from Sh5.48 trillion in December 2024 to Sh6.12 trillion in December 2025, according to the CBK.
The banking sector’s total net assets also increased by 10.3 per cent, from Sh7.57 trillion to Sh8.35 trillion over the same period.
Profit before tax rose by 17.7 per cent to Sh306.3 billion, while gross loans increased by 6.8 per cent.
The growth in deposits therefore forms part of a wider expansion in the banking sector rather than an isolated increase in the number of high-balance accounts.
What the numbers say about Kenya’s economy
The data presents a more nuanced picture than a simple story about a widening wealth gap.
On one hand, the increase in accounts holding at least Sh500,000 indicates growth in the number of relatively large deposit balances recorded by commercial banks.
On the other, the data does not tell us how much money each group holds in aggregate, who owns the accounts, whether the balances represent income, business working capital, institutional funds or accumulated savings, or how those account holders’ wealth compares with that of people holding assets outside the banking system.
Land, property, businesses, shares, pension funds and government securities, for example, are not captured by simply counting bank accounts.
That makes the CBK figures valuable but limited.
The bigger story is financial resilience
The more significant development may be the growth in Kenya’s overall deposit base.
An increase in customer deposits to Sh6.12 trillion suggests that substantial amounts of money were being held within the formal banking system by the end of 2025. The increase in larger-balance accounts occurred alongside this broader expansion.
For households, higher savings can provide a buffer against emergencies and economic shocks. For businesses, deposits provide liquidity for operations and investment. For banks, a stronger deposit base provides an important source of funding for lending and investment.
But the distribution of those deposits remains an important question — one that account-count data alone cannot fully answer.
A figure worth watching
The 781,977 high-balance accounts are therefore best understood as one indicator of Kenya’s financial landscape, not a definitive measure of the country’s wealthy population.
What the CBK data establishes is clear: commercial-bank accounts with at least Sh500,000 increased by 5.7 per cent between December 2024 and December 2025, while total customer deposits climbed by 11.6 per cent to Sh6.12 trillion.
The next question is whether this growth in financial wealth and deposits can translate into broader household savings, productive investment and greater financial resilience across Kenya’s economy.
For now, the banking data tells a story of a sector holding considerably more money — while leaving the harder question of who ultimately benefits from that growing pool of wealth open for further investigation.